
Paternity pay for self employed parents remains a significant financial concern in the UK, particularly for freelancers, sole traders, contractors and small business owners preparing to welcome a child.
As of October 2026, self-employed fathers and partners are not entitled to Statutory Paternity Pay (SPP) solely on the basis of their self-employment.
Unlike eligible employees, they have no automatic statutory right to paid paternity leave. However, limited company directors receiving qualifying employment income, people combining employment with self-employment, and families with an employed partner may have additional options.
The statutory paternity pay rate increased to £194.32 per week from 6 April 2026, equivalent to a maximum of £388.64 over two weeks for eligible workers.
Meanwhile, employment reforms introduced in April 2026 made paternity leave available from the first day of employment in Great Britain, without removing the existing service requirements for statutory pay.
Our analysis of the current employment framework highlights an important distinction: being self-employed does not prevent someone from taking time away from their business, but it does not create a statutory entitlement to payment for that period.
For entrepreneurs, the practical challenge is therefore wider than eligibility. It involves household income, business cash flow, National Insurance, financial assistance and maintaining customer relationships during parental leave.
Can You Get Paternity Pay If You Are Self Employed in the UK?
The short answer is no, if your only working status is genuinely self-employed.
The UK statutory paternity pay system operates primarily through employment and payroll arrangements. Someone running a business as a sole trader cannot normally claim SPP directly from HMRC or the Department for Work and Pensions.
Nevertheless, eligibility is not determined simply by whether someone describes themselves as a business owner.
A director who is also an employee of their limited company may qualify. Likewise, a freelancer who also works in a separate PAYE job may qualify through that employment.
Paternity Pay Eligibility by Employment Status
| Employment status | Statutory paternity pay | Statutory paternity leave |
| Sole trader | No | No |
| Self-employed freelancer | No, from freelance work alone | No |
| Self-employed business partner | No, from partnership profits alone | No |
| Limited company director | Potentially, through qualifying employment | Potentially, depending on employment status |
| PAYE employee | Yes, if qualifying conditions are met | Yes, from day one in Great Britain |
| Employed and self-employed | Potentially, through PAYE employment | Through qualifying employment |
| Agency or casual worker | Potentially, depending on employment and earnings arrangements | Depends on employee status |
| Both parents self-employed | Neither qualifies solely through self-employment | No statutory entitlement solely through self-employment |
The financial distinction between a sole trader and a limited company director becomes particularly important when planning parental leave.
A business owner considering different trading structures should understand the broader implications of operating as a sole trader or limited company rather than changing their business structure solely to obtain statutory benefits.
Importantly, incorporation alone does not guarantee entitlement. Employment status, payroll history, earnings and qualifying service must all be considered.
How Much Is Paternity Pay in the UK for 2026/27?
For the 2026/27 tax year, eligible employees can receive Statutory Paternity Pay at the lower of:
- £194.32 per week.
- 90% of average weekly earnings before tax.
Payments are available for up to two weeks and are normally processed through the employer’s payroll, with applicable Income Tax and National Insurance deductions.
For someone who is exclusively self-employed, the statutory payment remains £0.
Statutory Paternity Pay Rates: 2025 vs 2026
| Payment detail | 2025/26 | 2026/27 |
| Maximum weekly SPP | £187.18 | £194.32 |
| Maximum two-week SPP | £374.36 | £388.64 |
| Minimum average weekly earnings | £125 | £129 |
| Maximum statutory leave | 2 weeks | 2 weeks |
| Lower earnings calculation | 90% | 90% |
| SPP for solely self-employed parents | £0 | £0 |
The weekly statutory rate has increased by approximately 3.81% compared with 2025/26. However, the increase applies only to eligible recipients and has not created a new entitlement for self-employed parents.
Our financial assessment suggests that the headline payment should not be confused with full earnings protection. Even eligible employees earning substantially more than £194.32 per week can experience a considerable reduction in income.
How Much of Your Normal Income Does Paternity Pay Replace?
| Average weekly earnings | Weekly statutory pay | Earnings replacement rate |
| £129 | £116.10 | 90% |
| £200 | £180.00 | 90% |
| £250 | £194.32 | 77.7% |
| £500 | £194.32 | 38.9% |
| £1,000 | £194.32 | 19.4% |
Figures are illustrative, before payroll deductions, and assume the employee satisfies all eligibility conditions.
An employed father earning £500 per week would ordinarily receive £1,000 over two working weeks. Statutory Paternity Pay would replace £388.64 of this amount, leaving a gross income difference of £611.36.
By comparison, a sole trader who normally generates £500 per week in personal earnings may have no income replacement when completely stopping work, although previously completed work could still generate payments.
This is why financial preparation matters even for parents who qualify for statutory support.
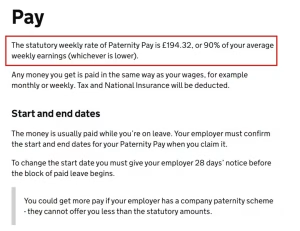
Official 2026/27 Statutory Paternity Pay rate of £194.32 per week, subject to the 90% earnings rule.
What Changed to Paternity Leave in April 2026?
One of the most important developments in UK employment law occurred on 6 April 2026.
Under changes introduced through the Employment Rights Act 2025, qualifying employees in England, Scotland and Wales gained access to statutory paternity leave from their first day of employment.
Previously, employees generally needed 26 weeks of continuous employment before qualifying for paternity leave.
However, the reform changed eligibility for leave, not the qualifying conditions for statutory paternity pay.
| Employment right | Before 6 April 2026 | From 6 April 2026 |
| Paternity leave | Generally required 26 weeks’ service | Day-one employee entitlement |
| Statutory paternity pay | 26-week service requirement | 26-week requirement retained |
| Unpaid parental leave | Generally required one year’s service | Day-one employee entitlement |
| Paternity leave after Shared Parental Leave | Previously restricted | Now permitted |
| Self-employed paternity entitlement | No statutory entitlement | No statutory entitlement |
The day-one reforms do not apply to Northern Ireland, where separate employment legislation continues to govern paternity leave.
For entrepreneurs, this reform creates an interesting distinction. A person who moves into qualifying employment shortly before becoming a parent could potentially access unpaid statutory paternity leave, even if they have not worked long enough to receive statutory paternity pay.
A genuinely self-employed person does not automatically acquire these employment rights simply because the law has changed.
The reform is therefore important but should not be interpreted as the introduction of paid paternity leave for all UK workers.
What Are the Eligibility Requirements for Statutory Paternity Pay?
To qualify for statutory paternity pay in 2026/27, an individual generally needs to satisfy several conditions relating to employment, earnings, family responsibility and notification.
The eligibility requirements include:
- Having continuous qualifying employment for at least 26 weeks by the end of any day in the qualifying week, normally the 15th week before the expected week of childbirth.
- Earning at least £129 per week on average before tax during the relevant earnings period.
- Remaining employed up to the child’s birth, subject to special circumstances.
- Being the child’s father, qualifying partner, adopter or intended parent under the applicable rules.
- Taking leave to care for the child or support the parent giving birth.
- Providing the required notice and declarations.
The earnings calculation typically examines an eight-week relevant period, although special payroll rules apply to some workers and directors.
Does Self-Employment Income Count Towards the £129 Earnings Requirement?
Ordinary sole-trader profits do not count as employment earnings for Statutory Paternity Pay.
For example, suppose a freelance graphic designer earns £800 per week from client projects and receives no PAYE employment income.
Despite earning well above £129 weekly, the freelancer does not qualify for SPP through that business activity.
Now consider someone earning £800 from freelance work and £200 per week from a separate PAYE role.
If the PAYE employment independently meets the necessary service, earnings and other eligibility conditions, statutory paternity pay may be available through that employer.
The £800 freelance income does not increase the amount of SPP calculated by the employer.
This distinction is particularly important for modern professionals who combine contracting, consultancy and part-time employment.
Can a Self-Employed Limited Company Director Claim Paternity Pay?
A limited company director may be in a different position from a sole trader because their company is a separate legal entity.
Directors can receive remuneration through PAYE, and eligible director earnings can count towards Statutory Paternity Pay.
However, being registered as a company director does not automatically establish a statutory entitlement. The director must meet the relevant conditions, including qualifying employment, earnings and continuity requirements.
Salary, Dividends and Director Eligibility
Consider a business owner operating through a UK private limited company.
The company generates £80,000 in annual revenue, but the director receives much of their personal income through dividends.
For statutory paternity pay purposes, the director’s company turnover and dividend income are not equivalent to qualifying employment earnings.
The relevant figure is qualifying remuneration, calculated according to HMRC’s rules for directors.
| Director income | Normally relevant to SPP? |
| Contractual PAYE salary | Yes, subject to qualifying conditions |
| Qualifying director’s fees | Potentially |
| PAYE bonus | Potentially |
| Shareholder dividends | No |
| Company turnover | No |
| Retained company profits | No |
| Director’s loan withdrawals | Not automatically |
Our analysis identifies this as one of the most significant eligibility issues for owner-managed businesses.
Directors who pay themselves a relatively small salary and take additional profits as dividends should review their payroll arrangements before assuming they qualify.
HMRC also operates specific average weekly earnings calculations for company directors, particularly where remuneration is irregular or determined through board or shareholder decisions.
A last-minute salary adjustment does not necessarily establish eligibility, and artificially changing remuneration without proper commercial, payroll and tax treatment may create compliance problems.
Company owners should also understand their responsibility for filing company accounts and maintaining accurate financial records, particularly when personal remuneration and company funds are being managed separately.
Can the Company Recover Paternity Pay From HMRC?
Where a director legitimately qualifies and the company pays Statutory Paternity Pay, the employer may recover some or all of the statutory payment through HMRC.
The 2026/27 recovery arrangements are:
| Employer category | Statutory payment recovery |
| Standard qualifying employers | 92% |
| Employers qualifying for Small Employers’ Relief | 109% |
For the 109% recovery rate, the employer’s total Class 1 National Insurance contributions for the preceding tax year must generally be £45,000 or less.
For example, if an eligible small company pays £388.64 in statutory paternity pay, a 109% recovery calculation would produce approximately £423.62.
The additional amount is compensation provided under the statutory recovery scheme, not an extra payment that the parent can claim personally.
If the employer cannot afford to make statutory payments, HMRC also provides an advance-funding application process for eligible employers.
This does not establish entitlement for an ineligible business owner.
Can Freelancers, Contractors and Gig Workers Receive Paternity Pay?
Not everyone labelled a freelancer or contractor has the same legal employment status.
Some freelancers operate genuinely independent businesses. Others work under arrangements that may give them employee or worker rights, depending on the actual relationship with the business paying them.
Statutory paternity leave and statutory paternity pay are also subject to different employment-status tests.
A worker who is not legally an employee may still qualify for statutory paternity pay in certain circumstances, even without entitlement to statutory paternity leave.
Therefore, it is important to examine:
- Whether the individual is paid through PAYE.
- Whether earnings are subject to Class 1 National Insurance arrangements.
- How long the person has worked under the relevant engagement.
- Whether the contractual relationship establishes employee or worker status.
- Whether statutory pay conditions are satisfied.
An agency worker receiving qualifying employment earnings should not automatically assume they are excluded.
Equally, registering as self-employed with HMRC does not guarantee that every engagement is genuinely self-employed for employment-law purposes.
For professionals balancing client work and business operations, understanding the financial and administrative requirements of running a consulting business can help distinguish commercial income from employment income.
Can Self-Employed Fathers Claim Shared Parental Leave and Pay?
Shared Parental Leave (SPL) allows eligible working parents to share up to 50 weeks of leave and up to 37 weeks of statutory pay following the birth or adoption of a child.
However, a self-employed parent cannot personally claim statutory Shared Parental Leave or Statutory Shared Parental Pay solely through self-employment.
An important exception concerns households where one parent is self-employed and the other is an eligible employee.
The employed partner may qualify for Shared Parental Leave and Pay if the family satisfies the relevant conditions.
How Does Shared Parental Leave Work With a Self-Employed Partner?
For certain shared parental leave arrangements, the partner’s employment and earnings test requires them to have:
- Worked for at least 26 weeks during the 66 weeks before the baby’s expected birth.
- Earned at least £30 per week in any 13 of those 66 weeks.
Those weeks do not necessarily need to be consecutive, and qualifying self-employment may count towards this partner test.
The employee seeking Shared Parental Leave must also satisfy their own eligibility requirements.
This means self-employment can help establish a partner’s eligibility for the employed parent’s shared parental entitlement, even though it does not create a personal SPL entitlement.
Examples of Different Household Arrangements
| Family circumstances | Potential parental support |
| Father self-employed, mother employed | Mother’s employment-related entitlements; father cannot personally claim SPL through self-employment |
| Mother self-employed, father employed | Mother may receive Maternity Allowance; father may qualify for SPP and SPL/ShPP |
| Both parents employed | Both may qualify for applicable statutory arrangements |
| Both parents self-employed | Neither qualifies for SPL/ShPP solely through self-employment; birth parent may qualify for Maternity Allowance |
| One parent is a qualifying employee-director | Employment-related entitlements may be available if statutory conditions are met |
Where the birth parent receives Maternity Allowance, the employed partner may be able to access Shared Parental Leave and Pay when the Maternity Allowance period is formally curtailed and other conditions are met.
The family should consider the financial implications before making that decision, because maternity payments and shared parental payments cannot simply be duplicated for the same entitlement period.
Can Self-Employed Fathers Claim Maternity Allowance Instead?
No. Maternity Allowance is not a general-purpose parental payment available to both parents.
It is primarily intended to support eligible people who are pregnant or have recently given birth and cannot receive Statutory Maternity Pay.
Self-employed fathers cannot claim it simply because they are taking time off to care for a newborn.
For an eligible self-employed birth parent, the 2026/27 payment can range from £27 to £194.32 per week for up to 39 weeks, depending on qualifying circumstances and National Insurance contributions.
| Comparison | Statutory Paternity Pay | Maternity Allowance |
| Maximum weekly payment | £194.32 | £194.32 |
| Maximum payment period | 2 weeks | 39 weeks |
| Available through qualifying employment | Yes | In certain circumstances where SMP is unavailable |
| Available to eligible self-employed birth parents | No, through self-employment | Yes |
| Available to self-employed fathers as a paternity substitute | No | No |
This highlights a significant structural difference between maternity and paternity support.
For eligible self-employed mothers, National Insurance contribution history can influence Maternity Allowance entitlement. There is no equivalent system through which a self-employed father can build up statutory paternity pay rights simply by paying Class 2 or Class 4 National Insurance.
Our assessment is that National Insurance contributions should not be treated as a universal entitlement to every statutory family benefit.
Some benefits are contribution-related, some are earnings-related and others are determined by employment status.
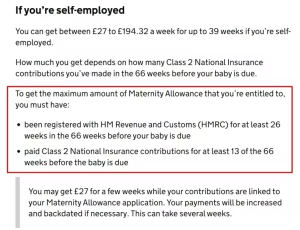
Official Maternity Allowance payment range for self-employed birth parents, illustrating the difference between maternity support and the absence of an equivalent self-employed paternity allowance.
What Financial Support Is Available for Self-Employed Fathers in 2026?
Although the UK does not currently offer a dedicated self-employed paternity allowance, families may qualify for other financial assistance.
These schemes do not replace statutory paternity pay directly, but they can help with household expenses and the additional costs associated with welcoming a child.
Financial Assistance Available to Self-Employed Parents
| Financial support | 2026/27 amount | Main eligibility consideration |
| Child Benefit – eldest or only child | £27.05 weekly | Responsibility for an eligible child |
| Child Benefit – additional child | £17.90 weekly | Responsibility for additional eligible children |
| Universal Credit | Depends on circumstances | Household income, savings and other eligibility rules |
| Sure Start Maternity Grant | £500 one-off | Usually first child and qualifying benefits |
| Scotland Pregnancy and Baby Payment | Depends on circumstances | Scottish residence and eligibility |
| Council-level assistance | Varies | Local support rules and financial circumstances |
| Partner’s statutory parental payments | Up to applicable statutory rates | Partner’s qualifying employment and parental entitlements |
Child Benefit
Child Benefit is one of the most relevant forms of financial assistance for self-employed parents because entitlement does not depend on being an employee.
From 6 April 2026, the weekly payment is £27.05 for the eldest or only child and £17.90 for each additional child.
For one qualifying child, the £27.05 weekly payment is equivalent to approximately £1,406.60 annually.
However, parents need to consider the High Income Child Benefit Charge.
Where either partner’s adjusted net income exceeds £60,000, some Child Benefit may need to be repaid through the tax system. Under the current rules, the charge reaches 100% when adjusted net income reaches £80,000.
Even where a family chooses not to receive Child Benefit payments, claiming can still be relevant for National Insurance credits.
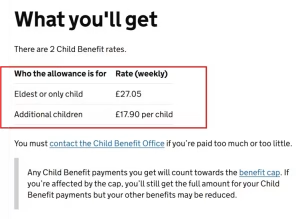
Official Child Benefit weekly payment rates for the 2026/27 tax year, showing £27.05 for the eldest child and £17.90 for additional children.
Universal Credit
Self-employed parents experiencing reduced household income may qualify for Universal Credit.
Eligibility depends on multiple factors, including household earnings, savings, housing costs and family circumstances.
As a general rule, claimants must have £16,000 or less in relevant money, savings and investments, subject to applicable exclusions and rules.
However, Universal Credit operates differently for self-employed people.
If someone is classed as gainfully self-employed, the Department for Work and Pensions may apply a minimum income floor when calculating their entitlement.
This means a reduction in actual business earnings does not necessarily produce an equivalent increase in Universal Credit.
The minimum income floor may not apply in certain circumstances, including an eligible business start-up period or where work-related requirements differ because of caring responsibilities.
Self-employed claimants also need to report their business income and allowable expenses monthly, including periods when little or no income is received.
For this reason, we would not recommend treating Universal Credit as a guaranteed replacement for lost freelance earnings.
Sure Start Maternity Grant and Other Support
Eligible families in England, Wales and Northern Ireland may receive a £500 Sure Start Maternity Grant.
This is generally available where a family is expecting its first child and receives certain qualifying benefits, although exceptions exist.
Scotland operates a separate Pregnancy and Baby Payment scheme.
Parents should check eligibility early because some grants have specific application deadlines.
How Much Income Could a Self-Employed Father Lose During Paternity Leave?
For business owners, the cost of parental leave depends on more than the number of days spent away from work.
Income may stop temporarily, but business expenses can continue.
Rent, insurance, subscriptions, finance repayments, equipment costs and supplier commitments may all remain payable even when the business owner is not actively trading.
Our analysis suggests that entrepreneurs should calculate both their personal income gap and their unavoidable business cash requirements.
Example: Self-Employed Father Taking Two Weeks Off
Assume a sole trader normally generates £700 per week in personal earnings after variable business costs but before unavoidable fixed overheads.
| Financial item | Two-week amount |
| Expected personal earnings not generated | £1,400 |
| Continuing business overheads | £240 |
| Statutory Paternity Pay | £0 |
| Estimated cash requirement | £1,640 |
| Illustrative 10% contingency | £164 |
| Suggested planning reserve | £1,804 |
This is a hypothetical cash-flow planning example, not an estimate of average UK self-employed earnings. Actual requirements depend on existing reserves, ongoing receipts, expenses and trading arrangements.
In this example, the business owner would ideally have around £1,804 available before beginning leave if no other income was expected to cover these costs.
However, not all time away from business creates an immediate reduction in revenue.
A consultant might continue receiving payments for previously completed projects, while a tradesperson paid only after finishing new jobs could experience a sharper income interruption.
This is why profitability and cash flow need to be analysed separately.
The same issue affects wider business sustainability, as explored in the relationship between startup success and cash-flow management.
How Much Should You Save Before Taking Paternity Leave?
There is no single reserve amount suitable for every self-employed father.
A useful calculation is:
Parental leave reserve = Expected household income shortfall + unavoidable business expenses + contingency − confirmed income available during leave.
A self-employed parent planning two weeks away from work might save enough to cover those two weeks and additional cash-flow delays.
Someone expecting four to six weeks of reduced activity may need a larger reserve.
When creating the forecast, separate money already owed by clients from income that depends on work not yet completed.
An unpaid invoice is not the same as cash in the bank.
How Can Self-Employed Parents Prepare Their Businesses for Paternity Leave?
Paternity leave requires operational planning as well as household budgeting.
For many founders, the immediate issue is not whether they can stop working for two weeks. It is whether their business can continue meeting its obligations without their daily involvement.
1. Prepare a Cash-Flow Forecast
Create a forecast covering at least the period before, during and immediately after the planned absence.
Include expected customer receipts, supplier payments, taxes, loan repayments and essential household spending.
A conservative forecast should consider what happens if a major customer pays late.
2. Review Existing Contracts
Freelancers and consultants should examine delivery deadlines, service commitments and cancellation provisions.
For example, a self-employed IT consultant responsible for a time-sensitive implementation may need to arrange a suitable replacement before the expected birth.
Clients should receive realistic delivery commitments rather than assumptions that work can continue normally.
3. Build an Emergency Reserve
A dedicated parental leave reserve helps prevent the family from using business funds needed for tax or operating expenses.
Where possible, separate the reserve into personal and business components.
This also helps avoid confusing company assets with personal money, particularly for limited company directors.
4. Arrange Temporary Business Support
Depending on the nature of the business, temporary support could include:
- A subcontractor completing agreed client work.
- An employee handling urgent customer enquiries.
- An accountant overseeing upcoming payment deadlines.
- Automated invoicing and payment reminders.
- A trusted colleague managing essential operational decisions.
Any temporary arrangement should comply with contractual, confidentiality, insurance and employment obligations.
5. Plan the Return to Work
Some self-employed parents find it easier to return gradually rather than immediately resume a full workload.
For example, a business owner might reduce client commitments by 50% during their first week back.
That figure is a planning choice, not a statutory entitlement.
The appropriate arrangement depends on business demand, financial reserves, caregiving responsibilities and the availability of support.
How Financially Prepared Are You for Self-Employed Paternity Leave?
To make preparation more measurable, we developed a simple five-part planning scorecard.
This is an editorial budgeting tool rather than an official government assessment or a survey-based rating.
Each completed condition contributes 20 percentage points.
| Financial preparedness indicator | Score |
| Essential household spending is covered for the planned absence | 20% |
| Continuing business overheads are funded | 20% |
| Tax and National Insurance reserves remain protected | 20% |
| Client deadlines and business continuity arrangements are in place | 20% |
| Partner entitlements and relevant family benefits have been checked | 20% |
| Maximum preparedness score | 100% |
A score of 100% means all five planning conditions have been addressed, not that the individual faces no financial risk.
Someone scoring 60% has completed three of the five preparations and should identify which remaining areas could create the greatest financial pressure.
Unlike statutory eligibility, this score depends on the individual’s own circumstances and should not be interpreted as a prediction of benefit entitlement.
What Happens With Paternity Pay in Adoption and Surrogacy Cases?
Self-employed people adopting a child or becoming parents through surrogacy arrangements face similar limitations.
Statutory Paternity Pay and Statutory Adoption Pay are linked to qualifying employment arrangements rather than simply having responsibility for a new child.
A genuinely self-employed adopter is not automatically entitled to statutory adoption leave or adoption pay.
Similarly, a self-employed intended parent in a surrogacy arrangement cannot claim statutory paternity pay solely because they have become a parent.
However, an eligible employee may qualify for statutory parental entitlements, subject to the specific rules for adoption or surrogacy.
For surrogacy, parental-order requirements may be relevant.
Families should examine the applicable arrangements before the expected birth or placement because statutory adoption and surrogacy notification rules differ from those for a straightforward birth.
What If a Baby Is Stillborn or Dies Shortly After Birth?
The statutory position is especially important in bereavement circumstances.
Eligible employees can retain certain paternity entitlements where a baby is stillborn after 24 weeks of pregnancy or is born alive and subsequently dies.
Bereavement-related statutory leave and pay arrangements can also apply, depending on eligibility.
However, self-employment alone does not establish an equivalent statutory paternity or parental bereavement payment entitlement.
Families in these circumstances may need specialist benefit, employment or financial guidance.
Will the UK Introduce Paternity Pay for Self-Employed Fathers in 2027?
The prospect of introducing a paternity allowance for self-employed parents has become an increasingly prominent policy issue.
The UK Government has been reviewing parental leave and pay arrangements, including whether the existing system adequately supports families excluded because of employment status.
In a parliamentary response on 11 September 2026, employment minister Kate Dearden acknowledged the limitations of the existing framework, stating:
This may leave self-employed parents and partners without support.
The Government confirmed that its Review of the Parental Leave and Pay System is examining the needs of working families who currently fall outside statutory entitlements.
Findings are expected in early 2027.
The issue was also raised in the House of Lords on 20 May 2026, when Baroness Penn questioned the fairness of excluding self-employed fathers from statutory paternity pay.
During that discussion, Baroness Lloyd of Effra confirmed that the review was considering possible support for self-employed fathers.
More recently, during a House of Commons exchange on 12 October 2026, Sir Stephen Timms confirmed that self-employed parents were expressly included within the review’s terms of reference.
These developments demonstrate that the issue is being actively considered at government level.
However, no statutory self-employed paternity allowance had been introduced as of 29 October 2026, and the review does not guarantee that new legislation or financial support will begin in 2027.
What Changes Could Be Considered?
Potential approaches discussed in the wider policy debate include introducing a dedicated paternal allowance, extending eligibility beyond traditional employment relationships or developing alternative income support arrangements.
The Women and Equalities Committee has previously recommended considering a paternity allowance for self-employed fathers and other excluded parents.
A payment system modelled on Maternity Allowance would require decisions about eligibility, contribution records, funding, payment duration and administration.
For business owners, the question is not simply whether a new allowance would exist. Its actual value would depend on payment rates, qualifying requirements and whether it reflects the irregular earnings patterns common in self-employment.
Until new rules are formally enacted and implemented, parents should plan around existing entitlements rather than anticipated reforms.
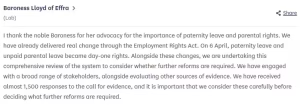
Parliamentary discussion on paternity leave for self-employed parents, including the Government’s confirmation that potential reforms are being considered in its parental leave and pay review.
Conclusion
Paternity pay for self employed fathers remains one of the significant gaps in the UK’s statutory family support system.
Although the maximum Statutory Paternity Pay rate increased to £194.32 per week in April 2026, genuinely self-employed parents remain excluded from claiming the payment solely through their business activity.
The introduction of day-one paternity leave rights for employees is an important employment reform, but it does not resolve the financial challenges faced by sole traders, freelancers and other independent business owners.
Our analysis suggests that self-employed parents should focus on three areas: confirming whether any qualifying employment entitlement exists, assessing available household financial support and protecting cash flow during the planned absence.
For company directors, understanding qualifying salary arrangements is particularly important. For families with one employed partner, Shared Parental Leave and Pay may offer additional flexibility.
The Government’s ongoing review offers the possibility of future reform. Until any new entitlement is confirmed, maintaining sufficient personal and business reserves remains one of the most practical ways to reduce financial pressure when welcoming a child.
Frequently Asked Questions About Paternity Pay for Self Employed Parents
1. Can Self-Employed Fathers Get Paternity Pay in 2026?
No. Genuinely self-employed fathers cannot receive Statutory Paternity Pay solely through self-employment. They may qualify separately through eligible PAYE employment or qualifying director remuneration.
2. How Much Paternity Pay Can a Self-Employed Father Claim?
The statutory payment is £0 for someone whose only working status is self-employed. Eligible employees can receive up to £194.32 per week for two weeks during 2026/27.
3. Can I Claim Paternity Pay Directly From HMRC?
No. Statutory Paternity Pay is normally claimed through an eligible employer. Sole traders cannot apply directly to HMRC for an equivalent paternity allowance.
4. Do Class 2 National Insurance Contributions Qualify Me for Paternity Pay?
No. Paying Class 2 National Insurance does not independently qualify a self-employed father for statutory paternity pay, although contribution records can be relevant to certain other benefits.
5. Can I Receive Paternity Pay if I Own a Limited Company?
Potentially. A director receiving qualifying employment remuneration may be eligible if the relevant earnings, service, employment and notification requirements are satisfied.
6. Can Self-Employed Fathers Take Two Weeks of Paternity Leave?
They can arrange two weeks away from their businesses, but they do not receive a statutory employment-law entitlement to that leave solely through self-employment.
7. Can I Claim Universal Credit While Taking Time Off for a Baby?
Possibly. Universal Credit can support eligible low-income households, including those with self-employed members. Actual entitlement depends on household finances, capital and applicable self-employment rules.
8. Will Self-Employed Fathers Receive Paternity Pay in 2027?
No confirmed new entitlement has been introduced. The Government’s parental leave and pay review is expected to report in early 2027, but any extension of support would require further policy decisions and implementation.