
For the 2026/27 tax year, most people in the UK have a standard Personal Allowance of £12,570. Dividing this across 12 months gives a monthly equivalent of £1,047.50, or roughly £1,048.
However, Income Tax is fundamentally based on annual taxable income rather than each month being treated as a completely separate tax period.
How much tax you actually pay can depend on your annual income, tax code, employment status, additional sources of income and where you live in the UK. National Insurance is also calculated separately from Income Tax, even though both may appear as deductions on an employee’s payslip.
Understanding these differences is particularly important for employees with changing monthly earnings, people with second jobs and those earning additional money through self-employment.
What Is the Tax-Free Monthly Income Limit for 2026/27?
For most taxpayers, the standard Personal Allowance for the 2026/27 tax year is £12,570.
Its simple monthly equivalent is:
£12,570 ÷ 12 = £1,047.50
Therefore, someone receiving a regular salary of around £1,047.50 per month would normally remain within the standard Personal Allowance if they had no other taxable income.
However, £1,047.50 should be viewed as a useful monthly equivalent rather than a separate monthly allowance that resets every month.
What Is the Personal Allowance?
The Personal Allowance is the amount of income most people can receive during the tax year before Income Tax becomes payable.
For 2026/27:
| Allowance | Amount |
| Standard Personal Allowance | £12,570 Per Year |
| Monthly Equivalent | £1,047.50 |
| Personal Allowance Taper Starts | Above £100,000 |
| Personal Allowance Fully Lost | £125,140 |
If adjusted net income rises above £100,000, the Personal Allowance is reduced by £1 for every £2 of income above that level.
Is £1,047.50 a Fixed Monthly Limit?
No. The actual Personal Allowance is annual.
For example, somebody could earn £700 one month and £1,300 the following month. That does not automatically mean they ultimately owe Income Tax simply because one month’s earnings exceeded £1,047.50.
PAYE normally uses a tax code to allocate tax-free income across the tax year. Previous earnings can therefore affect how much tax is deducted from later payslips.
On What Basis Is Income Tax Calculated in the UK?
Income Tax is primarily based on the amount of taxable income a person receives during a tax year, which runs from 6 April to 5 April.
HMRC considers different types of taxable income, which may include:
- Employment Income: Salary, wages, bonuses and taxable employment benefits
- Self-Employment Profits: Business income after allowable expenses
- Pension Income: Taxable private, workplace and State Pension income
- Property Income: Taxable profits from property
- Savings Income: Interest above applicable allowances
- Dividend Income: Dividends above available allowances
Allowances and applicable reliefs are then considered before the relevant tax rates are applied.
Is Tax Based on Monthly or Annual Income?
Income Tax liability is ultimately based on the tax year, although employees normally have tax deducted each time they are paid through PAYE.
This distinction matters when earnings fluctuate.
For example, someone could earn:
| Month | Income |
| April | £800 |
| May | £1,400 |
| June | £900 |
| July | £1,200 |
Looking only at May could make it appear that the person has exceeded their tax-free limit. However, their overall earnings and PAYE position during the tax year also need to be considered.
How Does Taxable Income Differ From Gross Income?
Gross income is generally the income received before tax and other deductions.
Taxable income is the amount that is actually considered when calculating Income Tax after relevant rules, deductions and allowances have been applied.
For a sole trader, this distinction is especially important. A business might receive £25,000 during the year but have £8,000 of allowable business expenses.
Its trading profit would therefore be:
£25,000 − £8,000 = £17,000
The sole trader is generally taxed on taxable profit rather than simply the total amount customers paid into the business.
What Are the UK Income Tax Rates for 2026/27?
For taxpayers in England, Wales and Northern Ireland, the standard Personal Allowance and main Income Tax structure for 2026/27 are:
| Annual Income | Main Tax Rate |
| Up To £12,570 | 0% |
| £12,571 To £50,270 | 20% |
| £50,271 To £125,140 | 40% |
| Above £125,140 | 45% |
The Personal Allowance may be lower for someone earning more than £100,000.
How Do the Main Tax Bands Work?
The UK uses a progressive tax system. Moving into a higher tax band does not mean the higher rate applies to all of your income.
For example, someone whose taxable income moves slightly into the higher-rate band does not suddenly pay 40% on their entire salary. Only the part falling within the higher-rate band is normally taxed at 40%.
This creates layers of taxation rather than one percentage being applied to everything a person earns.
Are Tax Rates Different in Scotland?
Yes. Scottish taxpayers have different Income Tax bands and rates for employment income, pensions and most other non-savings, non-dividend income.
For 2026/27, the Scottish rates are:
| Taxable Income Including Personal Allowance Position | Rate |
| Up To £12,570 | 0% |
| £12,571 To £16,537 | 19% |
| £16,538 To £29,526 | 20% |
| £29,527 To £43,662 | 21% |
| £43,663 To £75,000 | 42% |
| £75,001 To £125,140 | 45% |
| Above £125,140 | 48% |
The standard UK Personal Allowance still generally applies, but Scotland sets its own bands and rates for relevant earned income.
Does the Percentage of Tax You Pay Increase Every Year?
Income Tax percentages do not automatically rise every year.
For 2026/27, the main Income Tax rates on employment income in England, Wales and Northern Ireland remain at 20%, 40% and 45%.
What can change from one year to another are:
- Tax Rates: The percentage charged within a tax band
- Tax Thresholds: The amount of income at which a rate begins
- Allowances: The amount that can be received before certain taxes apply
- Special Income Rates: Different rates may apply to dividends, savings or other income
This means a person’s tax bill can increase even when the headline Income Tax percentage has not changed.
Why Can You Pay More Tax Even When Rates Stay the Same?
One reason is the freezing of tax thresholds.
The standard Personal Allowance has remained at £12,570 for several tax years. If wages rise while this allowance remains unchanged, a greater proportion of a person’s income can become taxable.
For example, consider someone whose salary increases:
Previous Salary: £28,000
New Salary: £31,000
Even if the basic Income Tax rate remains at 20%, more of the person’s salary sits above the £12,570 Personal Allowance.
This effect is sometimes described as fiscal drag. People can gradually pay more tax as their nominal earnings rise while tax thresholds remain fixed.
The current policy keeps the Personal Allowance at £12,570 and the higher-rate threshold at £50,270 until April 2031.
What Was the Latest Major Change to UK Income Tax?
The 2026/27 tax year did not introduce a new main rate structure for ordinary employment income in England, Wales and Northern Ireland. The basic, higher and additional rates remain 20%, 40% and 45%.
However, important changes affecting the wider Income Tax system have been introduced.
One of the major changes from 6 April 2026 was an increase in tax rates on dividend income.
The ordinary dividend rate increased from 8.75% to 10.75%, while the upper dividend rate increased from 33.75% to 35.75%. The additional dividend rate remains 39.35%.
Another significant policy change is the extension of frozen Income Tax thresholds. The Personal Allowance and key thresholds are now scheduled to remain frozen until April 2031.
What Changed in 2026/27?
For most employees, the main 2026/27 position is relatively stable:
- Personal Allowance: Remains £12,570
- Basic Rate: Remains 20%
- Higher Rate: Remains 40%
- Additional Rate: Remains 45%
- Higher-Rate Threshold: Remains £50,270
- Dividend Rates: Ordinary and upper rates increased from April 2026
Scotland also adjusted some of its band thresholds for 2026/27, although its Income Tax rates themselves remained unchanged.
How Did It Affect the Tax Structure?
The changes did not replace the progressive structure of UK Income Tax.
Instead, they changed particular parts of the system while keeping the main tax rates on employment income stable.
The continued threshold freeze is especially important because earnings may increase while the tax-free allowance does not.
Over time, this can move more income into taxable bands without the government increasing the headline 20%, 40% or 45% employment Income Tax rates.
How Much Tax Do You Pay at Different Monthly Income Levels?
The following examples assume regular employment income, a full £12,570 Personal Allowance and the main rates applying in England, Wales or Northern Ireland.
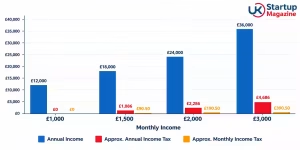
They show approximate Income Tax before considering National Insurance, pensions or other deductions.
| Monthly Income | Annual Income | Approx. Annual Income Tax | Approx. Monthly Income Tax |
| £1,000 | £12,000 | £0 | £0 |
| £1,500 | £18,000 | £1,086 | £90.50 |
| £2,000 | £24,000 | £2,286 | £190.50 |
| £3,000 | £36,000 | £4,686 | £390.50 |
These figures are illustrations. Actual PAYE deductions may vary because of tax codes, pension arrangements, previous earnings or other taxable income.
£1,000 Per Month
Someone earning £1,000 each month would receive £12,000 over a full year.
That is below the standard £12,570 Personal Allowance, so they would normally have no Income Tax liability if they had the full allowance and no other taxable income.
£1,500 Per Month
An employee earning £1,500 per month receives £18,000 annually.
After the £12,570 Personal Allowance, approximately £5,430 remains taxable. At a 20% basic rate, this produces about £1,086 of Income Tax annually, or an average of £90.50 per month.
£2,000 Per Month
A monthly salary of £2,000 equals £24,000 per year.
After deducting the standard Personal Allowance, approximately £11,430 remains taxable. At 20%, the annual Income Tax is around £2,286, equivalent to roughly £190.50 per month.
£3,000 Per Month
Someone earning £3,000 each month receives £36,000 annually.
Around £23,430 remains after the standard Personal Allowance. At the 20% basic rate, this gives approximately £4,686 in annual Income Tax, or around £390.50 per month.
How Does National Insurance Affect What You Pay?
National Insurance is separate from Income Tax. An employee can therefore have both Income Tax and National Insurance deducted from the same salary.
For most employees in 2026/27, the main Class 1 National Insurance rates are:
| Monthly Earnings | Employee NI Rate |
| Below £1,048 | Normally 0% |
| £1,048 To £4,189 | 8% |
| Above £4,189 | 2% On Earnings Above This Level |
The fact that the monthly National Insurance threshold is close to the monthly equivalent of the Personal Allowance can make the two systems appear identical, but they operate under different rules.
Self-employed people generally pay Class 4 National Insurance at 6% on profits between £12,570 and £50,270 and 2% on profits above the upper limit.
How Much Can Self-Employed People Earn Before Paying Tax?
Self-employed people generally receive the same standard £12,570 Personal Allowance as employees.
The important difference is what is measured.
Employees are generally taxed on taxable employment income, while sole traders are normally taxed on business profit.
For example:
Business Revenue: £20,000
Allowable Expenses: £5,000
Profit: £15,000
Assuming no other taxable income and a full £12,570 Personal Allowance, approximately £2,430 of the profit would remain above the Personal Allowance before applying the relevant Income Tax rate.
Are Sole Traders Taxed on Turnover or Profit?
Sole traders are normally taxed on taxable profits rather than turnover alone.
Turnover is the total income generated by the business before expenses. Profit is broadly the amount remaining after allowable business expenses have been deducted.
This distinction means a business taking £30,000 from customers does not necessarily create £30,000 of taxable trading profit.
How Does the £1,000 Trading Allowance Work?
The Trading Allowance can provide up to £1,000 of tax-free gross trading income in qualifying circumstances.
If eligible trading income is £1,000 or less, a person may not need to tell HMRC about that income in many circumstances.
Where gross trading income exceeds £1,000, the person may be able to use the £1,000 Trading Allowance instead of deducting actual business expenses when calculating taxable trading profit.
The Trading Allowance should not be confused with the £12,570 Personal Allowance. They are separate tax provisions.
What Happens If You Have More Than One Income Source?
Having several income sources does not normally provide several Personal Allowances.
For example, somebody may have:
- Main Job: £20,000
- Second Job: £5,000
- Freelance Profit: £3,000
Their tax position needs to consider the relevant income together rather than assuming each source receives its own £12,570 tax-free allowance.
A second job may also use a different tax code because the Personal Allowance is often allocated through the main employment.
The same principle is important for side hustles. Someone earning a salary already above £12,570 cannot normally claim another full Personal Allowance simply because they have started freelancing.
Why Might You Pay Tax Even When You Are Below the Allowance?
Seeing Income Tax deducted from a payslip does not necessarily mean that a person’s eventual annual tax liability will exceed the Personal Allowance.
Possible reasons include:
- Emergency Tax Code: HMRC or the employer may temporarily have incomplete information
- Month 1 Basis: Tax may be calculated using only the current pay period
- Previous Employment: Earlier income in the same tax year may affect PAYE
- Second Job: The Personal Allowance may already be allocated elsewhere
- Tax Code Adjustment: HMRC may adjust a code for benefits or previously underpaid tax
- Other Income: Income outside the current job can affect the overall tax position
Someone who has paid too much tax may be entitled to a refund once HMRC has the correct information.
How Much Can You Earn Before Paying Tax Per Month in 2026? – Summary
For the 2026/27 tax year, most UK taxpayers have a standard Personal Allowance of £12,570, equivalent to approximately £1,047.50 per month.
However, the £1,047.50 figure should not be treated as an independent monthly tax limit. Income Tax is ultimately based on taxable income during the tax year, while PAYE spreads tax calculations across individual pay periods.
In England, Wales and Northern Ireland, employment Income Tax continues to use main rates of 20%, 40% and 45%. Scotland operates separate bands and rates for relevant income.
Tax percentages do not automatically rise every year. A person can still pay more tax when wages increase while thresholds remain unchanged.
With key Income Tax thresholds frozen for several more years, understanding the difference between tax rates and tax thresholds is increasingly important when estimating future take-home pay.
Frequently Asked Questions
How Much Can I Earn Per Month Without Paying Income Tax?
With the standard £12,570 Personal Allowance, the simple monthly equivalent is around £1,047.50, although Income Tax liability is ultimately based on the tax year.
Is Income Tax Calculated Monthly or Yearly?
Income Tax liability is based on annual taxable income, but employees normally have deductions calculated throughout the year through PAYE.
Can I Earn More Than £1,048 in One Month Without Paying Tax?
Potentially, yes. Earning more in one month does not automatically determine your final tax liability because annual income and your PAYE position also matter.
Does the Percentage of Income Tax Increase Every Year?
No. Tax rates can remain unchanged for several years. Your tax bill may still increase if your earnings rise while tax allowances and thresholds remain frozen.
Do I Pay 40% Tax on My Entire Salary When I Become a Higher-Rate Taxpayer?
No. The 40% rate normally applies only to the portion of taxable income that falls within the higher-rate band.
Do I Get Another £12,570 Personal Allowance for a Second Job?
No. The Personal Allowance generally applies to your overall taxable income rather than separately to every job or source of earnings.
What Was the Main Income Tax Change for 2026/27?
Main employment Income Tax rates remained unchanged, but ordinary and upper dividend tax rates increased from April 2026, while the continued freeze of key tax thresholds remains important for taxpayers.