
The DWP Pension Banking Rules Changes 2027 are becoming increasingly important for UK pensioners, particularly those receiving Pension Credit or managing retirement savings across multiple bank accounts.
Following the introduction of new financial verification powers in October 2026, the Department for Work and Pensions can require banks to identify accounts that may not meet certain benefit eligibility conditions.
The changes form part of the Public Authorities (Fraud, Error and Recovery) Act 2025, which aims to identify incorrect benefit payments and reduce fraud.
However, these powers do not mean that every pensioner’s bank account will be monitored or that the DWP can freely examine spending habits.
Our analysis of the latest government rules identifies three particularly important developments for 2027:
- Banking verification: Financial institutions can be required to identify accounts meeting specified eligibility indicators.
- Pension Credit savings: The £10,000 capital disregard and the rules for calculating income from savings remain important.
- 2027 pension increases: The government has announced a 3.9% increase in the full new and basic State Pension rates, alongside higher Pension Credit minimum guarantees.
Understanding these changes matters for pensioners, former business owners and self-employed individuals who rely on several sources of retirement income.
What Are the Latest DWP Pension Banking Rule Changes for 2027?
The most significant development occurred on 26 October 2026, when the DWP confirmed that it had issued its first Eligibility Verification Notice.
This marked the beginning of operational use of its new bank-information powers.
The measure is designed to identify situations where benefit recipients may have undeclared savings or have spent longer overseas than their benefit rules permit.
| Important development | Date | Significance |
| Fraud, Error and Recovery Act received Royal Assent | 3 December 2025 | Established new statutory powers |
| Eligibility Verification Code of Practice published | 14 May 2026 | Set out safeguards and procedures |
| First Eligibility Verification Notice issued | 26 October 2026 | Began controlled implementation |
| Proposed 2027–28 benefit rates published | 11 November 2026 | Confirmed planned uprating figures |
| Main 2027–28 benefit uprating | 12 April 2027 | Higher pension and benefit rates expected to begin |
The implementation is proceeding through a controlled testing and learning phase rather than an immediate, unrestricted rollout across every bank account.
The broader system of bank-account checks is therefore expected to remain a significant issue for benefit administration during 2027.
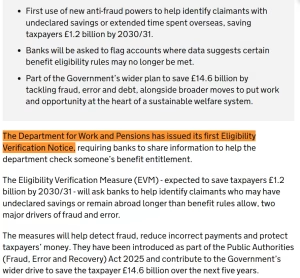
The DWP confirmed the first use of its new banking verification powers on 26 October 2026.
Which Pensioners Will Be Affected by the New DWP Bank Checks?
One of the biggest misunderstandings is that everyone receiving a State Pension will automatically become subject to the new verification system.
That is incorrect.
The Eligibility Verification Measure currently covers three benefits:
| Benefit | Covered by the new checks? |
| Pension Credit | Yes |
| Universal Credit | Yes |
| New Style Employment and Support Allowance | Yes |
| State Pension alone | No |
| Private or workplace pension alone | No |
| Attendance Allowance alone | No |
The State Pension is expressly excluded from the Eligibility Verification Measure.
This distinction is particularly important for pensioners who receive both a State Pension and Pension Credit.
While the State Pension itself is excluded, a person receiving Pension Credit may still have relevant accounts checked under the measure.
Pensioners confused by State Pension entitlements should therefore separate their contributory retirement income from means-tested benefits.
Our assessment suggests that understanding which benefit is being assessed is more useful than assuming all DWP payments follow identical banking rules.
What Bank Account Information Can the DWP Access in 2027?
Under the Eligibility Verification Measure, a financial institution checks its own records against indicators supplied by the DWP.
Where a relevant indicator is met, certain information can be returned.
This may include:
- Names of account holders.
- Bank account numbers and sort codes.
- Information about account balances.
- Details of relevant linked or joint accounts.
- Dates of transactions made in another country.
However, the measure does not give the department unrestricted visibility over financial transactions.
Banks cannot provide full transaction statements, shopping information, detailed spending histories or specific transaction locations through an Eligibility Verification Notice.
The DWP also cannot directly log into a pensioner’s online banking account or monitor it in real time using this measure.
This is different from other lawful information-gathering powers that may apply during a separate benefit investigation.
Minister for Innovation, Fraud and Debt Lilian Greenwood explained the government’s position in October 2026:
“We are not interested in where people do their weekly shop”
The statement reflects the intended distinction between eligibility verification and general financial surveillance.
The full procedure is explained in the DWP’s eligibility verification guidance.
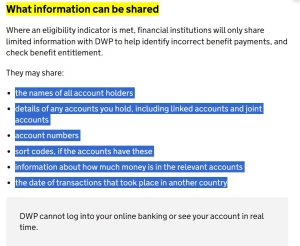
Official DWP guidance identifying the account information banks can share.
How Much Savings Can Pensioners Have Under the 2027 Banking Rules?
Pension Credit savings rules deserve particular attention because they differ significantly from those for Universal Credit.
For Pension Credit, the first £10,000 in eligible savings and investments is generally disregarded.
For every £500, or part of £500, above this amount, the DWP treats the capital as generating £1 in weekly income.
This is known as deemed income.
Pension Credit Savings Calculation for 2027
| Total assessable savings | Deemed weekly income | Annual equivalent |
| £8,000 | £0 | £0 |
| £10,000 | £0 | £0 |
| £10,500 | £1 | £52 |
| £12,000 | £4 | £208 |
| £16,000 | £12 | £624 |
| £20,000 | £20 | £1,040 |
| £30,000 | £40 | £2,080 |
These are illustrative deemed-income calculations, not bank charges or automatic deductions. The effect on an individual’s Pension Credit depends on their full entitlement assessment.
There is no fixed £16,000 upper savings limit for Pension Credit. A pensioner with more than £16,000 may still qualify depending on their income, capital and other circumstances.
For example, if an eligible pensioner has £16,000 in assessable savings, the resulting £12 weekly deemed income could reduce their Guarantee Credit by £624 over a full 52-week period, assuming their other circumstances remain unchanged.
From a retirement financial-planning perspective, the distinction matters because savings can reduce means-tested support without producing an equivalent amount of actual interest.
Our analysis also highlights the importance of considering several types of assets together, including current accounts, savings accounts, Cash ISAs and other investments. Different rules may apply to pension pots that have not yet been accessed.
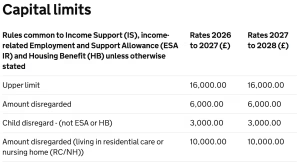
Pension Credit capital rules for 2027–28.
Will DWP Pension Payments Increase in 2027?
Yes. The DWP announced a 3.9% increase in the full new and basic State Pension rates for the 2027–28 tax year.
The standard minimum guarantee within Pension Credit is also due to rise by 3.9%.
| Pension payment | 2026–27 weekly rate | Proposed 2027–28 weekly rate |
| Full new State Pension | £241.30 | £250.70 |
| Full basic State Pension | £184.90 | £192.10 |
| Pension Credit – single minimum guarantee | £238.00 | £247.30 |
| Pension Credit – couple minimum guarantee | £363.25 | £377.40 |
The full new State Pension would therefore have an annual headline value of £13,036.40 across 52 weeks.
These increases are separate from the banking checks and do not change who falls within the Eligibility Verification Measure.
For pensioners managing a mix of income, the interaction between increasing pension payments and frozen tax thresholds is also important.
The wider implications of pensioner income tax and pension increases should therefore be considered alongside benefit eligibility.
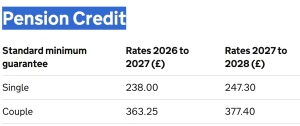
Proposed Pension Credit minimum guarantee rates for April 2027.
What Happens if a Pensioner Receives an Inheritance or Has Several Bank Accounts?
This is one of the most financially significant issues for people receiving means-tested retirement support.
Consider three illustrative situations.
Scenario 1: A Pensioner Receives £7,000 From an Inheritance.
If their existing assessable savings are £8,000, the additional inheritance could increase their capital to £15,000.
The resulting deemed weekly income would be £10, potentially affecting their Pension Credit entitlement.
The inheritance is not automatically disregarded simply because it is a one-off payment.
Scenario 2: A Retired Business Owner Has Several Accounts.
Someone may hold money in a current account, an emergency savings account and an investment account.
The Pension Credit assessment generally considers their relevant financial resources together rather than treating each bank account as having a separate £10,000 disregard.
Former company directors and self-employed individuals should also understand that private pension income, accessible capital and business assets can be subject to different assessment rules.
Scenario 3: A Pensioner Shares an Account With a Family Member.
Relevant joint or linked accounts can fall within the verification process, including certain accounts held by a non-claimant.
However, appearing as an account holder does not automatically establish that every pound in the account belongs to the pensioner.
Ownership and beneficial interest may need clarification.
These examples show why the underlying financial circumstances matter more than an isolated bank balance.
Can Spending Time Abroad Trigger a DWP Pension Banking Check?
Yes, where travel patterns suggest that the conditions for a relevant benefit may not have been met.
Pension Credit can normally continue during a temporary absence from Great Britain lasting four weeks or less, provided the relevant conditions are satisfied and the Pension Service is notified.
Longer periods may be permitted in specific circumstances, including bereavement or medical treatment.
Foreign transaction dates may therefore help identify cases requiring clarification. However, an overseas card transaction does not, by itself, establish how long a person has been abroad.
A pensioner living overseas permanently may still receive a UK State Pension if eligible, but Pension Credit follows different residency rules.
This distinction is particularly relevant to retirees who spend part of the year abroad.
Can the DWP Stop Pension Payments or Take Money Directly From a Bank Account?
An eligibility flag is not an automatic finding of fraud.
If the DWP receives information suggesting that a benefit may be incorrect, officials must assess the case and may ask for supporting documents or further explanations.
Payments could be affected following a review, particularly where relevant information is not supplied, but a bank flag alone does not automatically cancel an entitlement.
The Fraud, Error and Recovery Act also contains separate powers allowing direct deductions from bank accounts to recover certain established benefit debts.
These are not the same as routine Eligibility Verification Measures.
Direct deduction orders are subject to statutory procedures, notification requirements and financial hardship safeguards. Regular deductions are generally limited to 20% of a defined relevant amount, or 40% in certain fraud cases, subject to the law’s conditions.
Pensioners should not confuse account verification with an unrestricted power to seize retirement savings.
Where a claimant disagrees with a benefit decision, they can normally request mandatory reconsideration and, where applicable, pursue an appeal.
What Should Pensioners Do Before the 2027 Banking Checks Expand?
Financial organisation is more valuable than attempting to predict whether a particular account might be checked.
We recommend a practical compliance approach:
- Review savings: Calculate total assessable capital across relevant accounts and investments.
- Report changes: Notify the Pension Service about significant changes in savings, income, household arrangements and overseas travel.
- Keep records: Retain statements and documents explaining inheritances, gifts, pension withdrawals and unusual transfers.
- Update bank details: Make sure the DWP has the correct account information for payments.
- Respond promptly: If a benefit review begins, provide the requested information through verified official channels.
- Protect personal information: Check suspicious messages independently rather than sharing banking credentials.
Pensioners can also review the meaning of DWP SP on bank statements when reconciling their retirement income.
Changing the bank account receiving the State Pension remains a separate administrative process. It does not automatically alter benefit eligibility, but the Pension Service must be informed.
Those approaching retirement should consider the State Pension age changes alongside these financial checks.
Scams are another practical concern. Fraudsters may exploit news of stronger eligibility checks by sending threatening messages asking for immediate payment.
Understanding DWP text warnings and verifying an unfamiliar phone number can help prevent unnecessary financial losses.
How Might These Changes Affect Retirement Financial Planning Beyond 2027?
The significance of these rules extends beyond identifying inaccurate benefit awards.
For pensioners, financial security increasingly depends on coordinating different sources of income, including State Pension payments, occupational pensions, savings interest and means-tested support.
Our analysis identifies three important considerations.
First, a rise in State Pension income does not necessarily create the same increase in disposable income for everyone. Pension Credit assessments and pension taxation may affect the final outcome.
Second, greater verification makes accurate reporting more important, particularly when households experience changes following retirement, bereavement, inheritance or the sale of business assets.
Third, income-related support should not be confused with payments governed by separate rules, such as Winter Fuel Payment.
From a financial management perspective, the most effective response is to understand the rules for each benefit, maintain accurate records and review retirement cash flow periodically.
The DWP’s bank-checking powers may make discrepancies easier to identify, but they do not remove a pensioner’s right to have their circumstances properly assessed.
Final Outlook for 2027
The DWP Pension Banking Rules Changes 2027 represent a significant development in how the government verifies entitlement to certain benefits.
The first banking verification notices began in October 2026, while proposed pension upratings and existing capital rules establish the financial context for 2027.
For most State Pension recipients, the central concern should not be unrestricted banking surveillance. Instead, pensioners receiving means-tested support should understand which accounts and financial circumstances may be relevant to a claim.
Maintaining accurate records, reporting financial changes and understanding the difference between State Pension and Pension Credit rules will remain essential for protecting retirement income and avoiding preventable benefit disputes.
Frequently Asked Questions
Can the DWP check my bank account in 2027?
Yes, for specified benefits under the Eligibility Verification Measure. Banks can provide limited information when relevant indicators are met, but the DWP does not receive unrestricted account access.
Will the DWP check every pensioner’s bank account?
No. Receiving only the State Pension does not place someone within the new Eligibility Verification Measure. Pension Credit claimants are among those covered.
Is there a £16,000 savings limit for Pension Credit?
No. Pension Credit has no fixed upper capital limit. Savings above £10,000 generally create deemed income that may reduce entitlement.
Can the DWP check joint bank accounts?
Relevant joint and linked accounts can fall within the verification system. However, account ownership and the actual entitlement to funds must be considered.
Will my State Pension stop if I have £20,000 in savings?
No. State Pension entitlement is not normally means-tested against savings. However, savings may affect separate benefits such as Pension Credit.
Can the DWP see what I buy?
Not through an Eligibility Verification Notice. Banks cannot disclose full spending histories or shopping transactions under this measure.
What happens if the DWP makes an incorrect benefit decision?
A claimant can normally request mandatory reconsideration and may have further appeal rights. Supporting financial documents can help establish the correct entitlement.