
Are pensioners in the UK facing new home ownership restrictions in 2027? Could owning a £300,000 or £500,000 property prevent someone from receiving Pension Credit, and will the Department for Work and Pensions (DWP) start counting housing equity when assessing benefits?
These questions have become increasingly relevant as the UK approaches another round of pension and welfare adjustments.
The important news is that the DWP has not announced a new rule for 2027 requiring pensioners to sell their main homes or include the value of their primary residence in ordinary Pension Credit means-testing.
However, several confirmed changes will affect retirement income, benefit calculations and financial planning from April 2027.
The Government has announced a 3.9% increase in the Pension Credit standard minimum guarantee, while new benefit rates, financial verification arrangements and existing property assessment rules remain important considerations for homeowners.
Our analysis of DWP guidance, pension statistics and the 2027–28 benefit uprating announcement identifies a significant distinction between property wealth and money available to meet everyday living costs.
A pensioner may own a valuable home but have very little disposable income. The benefit system generally recognises that distinction.
For homeowners approaching retirement, the more important questions concern savings, second properties, inherited assets, mortgage costs and how changes in personal circumstances influence eligibility.
What Are the DWP Pensioner Home Ownership Rules Changes for 2027?
The DWP pensioner home ownership rules changes attracting attention in 2027 are largely connected to existing means-tested benefit arrangements and confirmed increases in pension support.
There is no verified nationwide policy making ordinary homeowners ineligible for Pension Credit simply because their primary residence exceeds a particular market value.
The distinction matters because retirement financial assessments are not the same as property taxation or local authority care-funding assessments.
DWP Home Ownership Rules: 2026 vs 2027
| Rule or benefit | Position in 2026 | Position for 2027 |
| Main residential property | Normally excluded from Pension Credit capital assessments | No announced change to this exemption |
| Second home | Usually assessed as capital, subject to exceptions | Existing rules continue |
| Pension Credit savings disregard | First £10,000 ignored | £10,000 remains unchanged |
| Pension Credit upper capital limit | No fixed upper limit | No fixed upper limit |
| Single Pension Credit minimum guarantee | £238 weekly | £247.30 weekly |
| Couple Pension Credit minimum guarantee | £363.25 weekly | £377.40 weekly |
| Capital deemed income | £1 weekly per £500 or part above £10,000 | Same calculation |
| Full new State Pension | £241.30 weekly | £250.70 weekly |
| Pension Credit qualifying age | Linked to State Pension age | Continues rising according to date of birth |
| Financial eligibility verification | New statutory verification framework | Relevant to claim accuracy, not a new home-equity tax |
The 2027–28 rates have been announced by the Government, with most increases scheduled to take effect from 12 April 2027, subject to the relevant implementation requirements.
One particularly important development came during October 2026, when the DWP publicly addressed the misconception that owning a home automatically prevents someone from claiming Pension Credit.
The department confirmed that home ownership itself is not included when determining normal Pension Credit entitlement.
This gives homeowners a much clearer basis for planning than speculation about potential future wealth assessments.
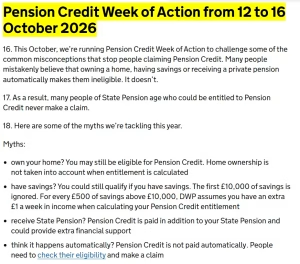
DWP’s October 2026 clarification confirms that owning a home does not automatically prevent a pensioner from receiving Pension Credit.
Can Pensioners Still Own Their Homes and Claim Pension Credit in 2027?
Yes. Pensioners can continue owning their homes while receiving Pension Credit, provided they satisfy the relevant income, residence, age and other eligibility requirements.
The DWP normally disregards the market value of a person’s primary residence when calculating capital for Pension Credit.
Consider two pensioners with very different housing circumstances.
One owns a £450,000 property outright, while the other owns a £175,000 flat with an outstanding mortgage.
If their assessable incomes, savings and other relevant circumstances are identical, the difference in the value of their main homes would not ordinarily result in different Pension Credit awards.
This is because the value of a home is not necessarily money available for groceries, energy bills or essential living expenses.
The position can differ where a property includes land or buildings that could reasonably be sold separately.
For example, an unusually large property containing a separately marketable plot of land could require closer assessment.
Nevertheless, the ordinary family home remains protected by the main-residence capital disregard.
From our financial analysis, one of the biggest mistakes pensioners can make is assuming that substantial housing equity automatically means they are too wealthy to qualify for retirement support.
Someone who is asset-rich but income-poor may still satisfy the eligibility conditions.
Understanding genuine entitlement is particularly important when evaluating State Pension payments and additional pension support rather than relying on headline payment announcements.
How Much Savings Can a Pensioner Have Before DWP Benefits Are Affected?
Savings and investments are more directly relevant to Pension Credit than the value of the main home.
Under the rules continuing into 2027, the first £10,000 of assessable capital is disregarded.
Above this level, the DWP calculates assumed or deemed weekly income.
For every £500, or part of £500, above £10,000, the department assumes the pensioner receives an additional £1 in weekly income.
This assumed income is included in the Pension Credit calculation even if the pensioner’s actual investment returns are different.
Pension Credit Savings Calculation Examples
| Total assessable savings | Amount above £10,000 | Assumed weekly income |
| £5,000 | £0 | £0 |
| £10,000 | £0 | £0 |
| £12,000 | £2,000 | £4 |
| £15,000 | £5,000 | £10 |
| £20,000 | £10,000 | £20 |
| £25,000 | £15,000 | £30 |
| £40,000 | £30,000 | £60 |
| £60,000 | £50,000 | £100 |
These calculations demonstrate why two homeowners with similar pension incomes can receive different benefits when their savings are substantially different.
Importantly, £10,000 is not a maximum savings limit for Pension Credit.
A person can have savings above that amount and still qualify if their assessed income remains sufficiently low.
There is no universal upper capital limit for Pension Credit, although high levels of capital can generate enough deemed income to eliminate entitlement.
What Happens if a Pensioner Has £15,000 in Savings and Owns a £350,000 House?
Consider an illustrative single pensioner with the following circumstances:
- Primary residence valued at £350,000.
- Total assessable savings of £15,000.
- Weekly assessable pension income of £200.
- No additional income or adjustments affecting their standard guarantee calculation.
The house is disregarded because it is the person’s main residence.
The savings generate £10 in weekly deemed income.
The resulting assessable weekly income is £210.
Using the announced 2027 standard minimum guarantee of £247.30:
£247.30 − £210 = £37.30 per week
The illustrative Pension Credit top-up is therefore £37.30 per week, equivalent to approximately £1,939.60 over 52 weeks.
This is a simplified financial example, not an entitlement decision. Actual payments can be affected by other income, household circumstances, additional needs and relevant benefit rules.
For retirement planning purposes, the calculation illustrates that the property value itself does not prevent a qualifying pensioner from receiving support.
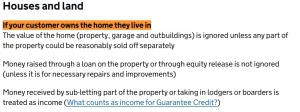
Official Pension Credit guidance explains why a pensioner’s main home is normally excluded from capital assessments while savings above £10,000 can affect entitlement.
What Will Change in Pension Credit Payments From April 2027?
One of the most significant confirmed financial developments for pensioners is the increase in Pension Credit payments for the 2027–28 financial year.
The Government announced that the standard minimum guarantee would rise by 3.9%, reflecting the annual earnings-linked uprating.
The increase is particularly relevant to low-income homeowners whose pension payments do not fully cover household expenditure.
Pension Credit Rates for 2026–27 and 2027–28
| Household | 2026–27 weekly rate | Announced 2027–28 rate | Weekly increase |
| Single pensioner | £238.00 | £247.30 | £9.30 |
| Pensioner couple | £363.25 | £377.40 | £14.15 |
A single pensioner receiving the full weekly top-up increase could see an additional £483.60 over 52 weeks, assuming their assessed income and circumstances remain unchanged.
For a pensioner couple, the increase in the standard minimum guarantee equals £735.80 over 52 weeks.
These figures represent changes in the guarantee thresholds. They do not mean every Pension Credit recipient automatically receives the full difference as additional cash.
A pensioner’s actual award depends on changes to their other assessable income and applicable additions.
In his 28 October 2026 parliamentary statement, Pat McFadden, Secretary of State for Work and Pensions, confirmed:
“The Standard Minimum Guarantee in Pension Credit will also increase by 3.9%”
The announcement demonstrates that the Government’s confirmed 2027 changes focus on maintaining retirement income support rather than introducing a new general property-value test.
Our assessment is that the increase should be considered alongside the State Pension’s 2027 uprating when preparing household budgets.
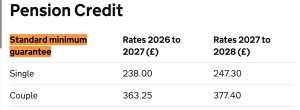
The DWP’s November 2026 benefit-rate publication confirms the announced Pension Credit minimum guarantee figures for 2027–28.
Will the DWP Count Second Homes and Inherited Properties in 2027?
Second properties are a more significant consideration than a person’s normal home when assessing Pension Credit.
The DWP can include the net market value of property that a claimant owns but does not occupy as their main residence.
This may include holiday homes, buy-to-let investments and inherited property.
However, the rules are not identical for every property.
Certain properties can be disregarded where specific conditions apply.
For example, exceptions may apply where a property is occupied by a qualifying close relative who has reached Pension Credit age or is sick or disabled.
Temporary disregards can also apply when someone is taking reasonable steps to sell a property.
Under the existing rules, a property being sold may qualify for a disregard lasting 26 weeks, potentially longer where reasonable difficulties justify an extension.
Therefore, inheriting a home or temporarily owning two properties does not necessarily mean the full value will immediately affect an award.
The individual circumstances and relevant property rights must be assessed.
Example: A Pensioner Owns a £200,000 Main Home and a £120,000 Rental Property
A pensioner who lives in their £200,000 house and separately owns a rental property valued at £120,000 may have that second property’s assessable net value included in their capital.
Outstanding secured debts and appropriate valuation deductions can affect the calculation.
Rental income may also be relevant under the applicable income rules.
The combination could substantially reduce or eliminate Pension Credit.
This differs from owning just the £200,000 home.
For pensioners considering buy-to-let investments, rental returns should be assessed alongside taxation, maintenance expenditure and benefit eligibility.
Potential changes to the taxation of rental property are a separate financial issue and should not be confused with DWP capital assessment rules.
Does Equity Release Affect Pension Credit for Homeowners?
Equity release can have a material effect on means-tested benefits, even though the primary residence itself remains disregarded.
Equity release products allow eligible homeowners to access money tied up in property.
However, there is a distinction between equity remaining inside the home and money released into a bank account.
The property’s normal market value is disregarded for Pension Credit purposes.
Money received through equity release and retained as accessible capital can affect the calculation.
For example, a homeowner with £7,000 in existing savings who receives £30,000 through equity release could have substantially more assessable capital than before.
Whether all the funds count immediately, and whether particular disregards apply, depends on the arrangement and how the money is used.
Certain funds intended for essential repairs or improvements may receive different treatment.
Equity release can also create borrowing costs, compound interest and reduced inheritance value.
Our assessment is that a pensioner receiving Pension Credit should obtain a benefits calculation before completing any equity release transaction.
The short-term benefit of accessing cash needs to be weighed against the possible reduction in future means-tested support.
Can Pensioners Give Their House to Their Children to Protect Benefits?
Giving away a house or substantial savings does not automatically remove those assets from a DWP assessment.
The department can apply deprivation-of-capital rules where someone deliberately disposes of capital to obtain or increase means-tested benefits.
The property transfer may also create separate inheritance, legal and tax complications.
A family considering this arrangement should review the potential consequences of transferring property while the former owner continues living there.
For example, inheritance tax when the second parent dies can involve different issues from Pension Credit entitlement.
Likewise, the tax treatment of pension wealth and estates follows separate rules.
DWP benefit eligibility and inheritance tax should not be treated as interchangeable systems.
Can Pensioner Homeowners Receive Support for Mortgage Interest in 2027?
Yes. Eligible pensioners who still have a mortgage may qualify for Support for Mortgage Interest (SMI).
SMI is designed to help with qualifying interest payments on a mortgage or certain home improvement loans.
For someone receiving Pension Credit, the usual maximum outstanding loan amount used in the SMI calculation is £100,000.
Certain transitional exceptions can allow a higher limit.
SMI is not a grant.
It is a recoverable loan, and interest accrues on the amount provided.
The loan is generally repaid when the property is sold or transferred, subject to applicable rules and exceptions.
Where someone receiving Pension Credit qualifies for SMI, support can begin from the date their Pension Credit entitlement starts.
However, SMI does not normally cover mortgage capital repayments, arrears or insurance costs.
As of November 2026, the Government lists a standard SMI calculation rate of 3.66% and a separate 4.5% interest rate on outstanding SMI loans. These are variable figures and should be checked before applying in 2027.
From a retirement cash-flow perspective, SMI may help protect monthly affordability, but it also creates a liability secured against the property.
A pensioner considering this option should assess the long-term borrowing cost and potential consequences for their estate.
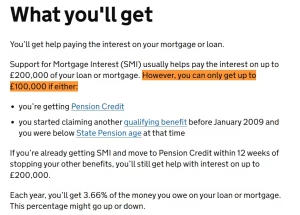
The Government’s SMI guidance explains the mortgage-interest support available to eligible Pension Credit homeowners and the limit used to calculate assistance.
Do Housing Benefit, Council Tax Reduction and Care Fees Follow the Same Property Rules?
No. One of the most important distinctions is that Pension Credit, Housing Benefit, Council Tax Reduction and residential care funding operate under different assessment arrangements.
A homeowner should not assume that an exemption under one scheme automatically applies to every other financial assessment.
| Financial support | Treatment of property |
| Pension Credit | Main home normally disregarded |
| Housing Benefit | Main residence generally disregarded as capital; mainly supports qualifying rental costs |
| Council Tax Reduction | Home ownership does not automatically prevent support; financial criteria apply |
| Support for Mortgage Interest | Support is a recoverable loan for eligible housing interest costs |
| Residential care funding | Property can become relevant when assessing permanent residential care costs |
| Inheritance Tax | Property can form part of a deceased person’s taxable estate |
Pension-age Housing Benefit generally has a £16,000 upper capital limit, but that limit does not apply in the same way to claimants receiving the Guarantee Credit element of Pension Credit.
The £10,000 lower capital disregard and tariff income calculations can remain relevant.
Council Tax Reduction is administered through local authorities, with different arrangements applying according to age, circumstances and the relevant scheme.
Some households may also qualify for property-related reductions independent of their Pension Credit entitlement.
For example, certain disability-related Council Tax reductions depend on the property’s adaptation and the resident’s qualifying needs.
What Happens if a Homeowner Permanently Moves Into a Care Home?
This is an important exception to the everyday rule that a person’s primary home is disregarded.
Where someone moves permanently into residential care, the property may no longer qualify as their normal home for benefit assessment purposes.
Different disregards can apply, including where a qualifying partner or close relative continues living in the property.
In England, local authority residential care financial assessments also have separate provisions, including a possible 12-week property disregard and deferred payment arrangements.
These should not be confused with Pension Credit rules.
The treatment of property can also differ across England, Scotland, Wales and Northern Ireland because social care funding systems are not identical.
Households facing permanent residential care should obtain specialist welfare and social care advice before selling, transferring or renting out a property.
How Do the DWP Rules Affect Married Pensioners and Mixed-Age Couples?
A pensioner’s relationship status can influence entitlement because benefit calculations may consider both partners’ income and capital.
For ordinary Pension Credit claims, couples usually need both partners to have reached the qualifying age.
Mixed-age couples, where one partner has reached State Pension age but the other has not, are generally directed towards Universal Credit for a new means-tested support claim.
However, transitional protection and existing claims can create exceptions.
Some couples who have continuously received qualifying benefits since before the May 2019 rule change retain protection.
This means mixed-age couples should not voluntarily close an existing award or change benefits without checking the consequences.
The distinction becomes particularly important because Universal Credit generally has a £16,000 upper capital limit, unlike Pension Credit.
The main home is ordinarily disregarded under Universal Credit too, but other savings and property interests may influence the calculation.
For older couples managing shared retirement finances, changes in income and household circumstances may also influence seasonal support, including Winter Fuel Payment arrangements for husbands and wives.
Another important 2027 consideration is the increase in State Pension age.
The qualifying age is moving gradually from 66 to 67 between April 2026 and March 2028.
An applicant’s exact eligibility date therefore depends on their date of birth.
What Do the Latest DWP Statistics Reveal About Pensioner Benefits?
One of the most significant findings in our analysis concerns the number of older households not claiming financial support for which they may qualify.
DWP statistics published in October 2026, covering the financial year ending 2025, show that only 62% of pensioner families entitled to Pension Credit actually claimed it.
That means an estimated 38% did not claim.
The statistics also estimated that up to 900,000 pensioner families were missing out on Pension Credit.
The amount of potential unclaimed support reached approximately £2.4 billion.
Pension Credit Take-Up Statistics
| Measure | Official estimate |
| Eligible pensioner families claiming Pension Credit | 62% |
| Eligible pensioner families not claiming | 38% |
| Share of available Pension Credit expenditure claimed | 74% |
| Families potentially missing Pension Credit | Up to 900,000 |
| Estimated annual unclaimed Pension Credit | Up to £2.4 billion |
| Average annual entitlement among non-claiming eligible families | Around £2,500 |
These are the latest published take-up estimates available as of November 2026, not forecasts for 2027.
The figures highlight a more immediate financial concern than speculation about new property restrictions.
Older homeowners may be missing out on legitimate support because they misunderstand the eligibility rules.
Our financial interpretation is that checking entitlement offers a more measurable opportunity than taking costly decisions based on unsupported rumours about housing wealth.
A pensioner who wrongly assumes that ownership of a £300,000 property disqualifies them could lose years of financial assistance simply by failing to apply.
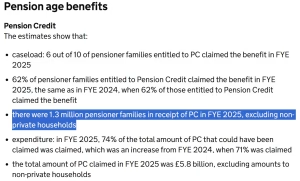
Official DWP statistics published in October 2026 show that a substantial proportion of eligible pensioner families do not claim Pension Credit.
Will the DWP Check Pensioners’ Bank Accounts and Property Ownership in 2027?
Financial verification is a genuine policy development, but it is important not to confuse eligibility checks with a new tax on pensioners’ homes.
The Public Authorities (Fraud, Error and Recovery) Act 2025 established a statutory framework for additional benefit eligibility verification.
The framework is relevant to specified benefits, including Pension Credit.
Under the arrangements, banks and financial institutions may be required to check accounts against prescribed eligibility indicators and provide specified information where the legal conditions are met.
This does not create a general power to confiscate a pensioner’s home.
Nor does it mean the DWP is introducing a new property tax.
The purpose is to identify discrepancies that could affect benefit entitlement.
Our review of the DWP bank-account eligibility checks suggests that accurate reporting of capital and changes in circumstances will become increasingly important for affected claimants.
Pensioners should also understand how the Eligibility Verification Measure differs from ordinary benefit reviews.
For example, someone receiving Pension Credit who inherits an investment property or receives a substantial equity release lump sum should report relevant changes.
The key issue is whether their assessable financial circumstances have changed, not whether the Government has started taxing their primary residence through the benefits system.
Which Home Ownership Situations Deserve the Most Attention Before 2027?
We assessed common retirement scenarios according to their practical importance for household budgeting, benefit reassessment and the potential financial consequences of getting the rules wrong.
The percentage ratings below are our editorial planning-priority scores, not official DWP risk percentages or statistical probabilities.
| Financial situation | Our priority rating | Main consideration |
| Inheriting an additional property | 95% | Property may become assessable capital |
| Releasing a large amount of housing equity | 90% | Accessible cash may affect Pension Credit |
| Owning a second or rental property | 90% | Property value and income may affect entitlement |
| Mixed-age couple changing benefits | 85% | Different capital rules and transitional protection |
| Moving permanently into residential care | 85% | Benefit and local authority property rules differ |
| Applying for SMI with an outstanding mortgage | 80% | Interest costs and future repayment liability |
| Living in an owned main residence with modest savings | 35% | Main home generally disregarded |
These scores reflect the level of financial planning attention we would assign to each scenario.
They should not be interpreted as predictions of whether the DWP will approve or reject a claim.
The most important practical finding is that a pensioner’s circumstances and access to liquid capital usually matter more than the headline market value of their home.
What Should Pensioner Homeowners Do Before the 2027 Rules Take Effect?
The most sensible approach is to review retirement income and property arrangements before major financial decisions are made.
- Review pension income and savings: Check State Pension, workplace pensions, private pensions, cash accounts, investments and any additional property interests.
- Confirm Pension Credit entitlement: Do not assume that home ownership disqualifies an application. Use the official Pension Credit calculator or seek benefits advice.
- Check changes to the household: A partner moving in, changes in caring responsibilities or moving to a different address can affect eligibility.
- Review mortgage obligations: Pensioners with outstanding housing debt should compare the benefits and long-term costs of SMI, equity release and lender support.
- Assess inherited assets carefully: Seek advice before selling, gifting or transferring property where means-tested benefits may be affected.
- Review other support: Pension Credit may provide access to additional help, while changes in taxable income can influence schemes such as the Winter Fuel Payment clawback.
- Keep accurate financial records: Retain pension statements, savings balances, property valuations and relevant correspondence.
Pensioners reviewing their payment history can identify how the State Pension appears on a statement through the DWP SP bank payment reference.
Anyone receiving unexpected requests for personal or financial information should also check current DWP text message warnings before responding.
How Can Pensioners Apply for Pension Credit?
Eligible applicants can normally begin their Pension Credit application up to four months before reaching the qualifying age.
Claims may also be backdated for up to three months where the relevant conditions were met during that period.
Applications require information about pension income, savings, investments and household circumstances.
The official application process is available through GOV.UK.
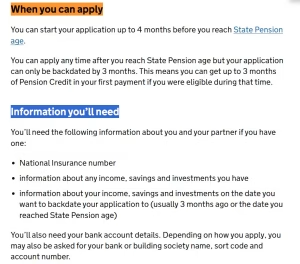
The official Pension Credit application guidance explains when pensioners can claim and which financial details are required.
Conclusion
The DWP pensioner home ownership rules changes for 2027 should be understood through confirmed benefit regulations rather than speculation about property wealth.
Owning a valuable primary residence does not automatically prevent someone from receiving Pension Credit, and there is no announced new nationwide rule requiring pensioners to surrender housing equity as a condition of ordinary Pension Credit eligibility.
The confirmed 2027 developments include a 3.9% increase in the standard minimum guarantee, alongside continuing rules for savings, additional properties and household income.
Our analysis suggests that pensioners should focus on checking their actual benefit entitlement, understanding the treatment of property-related assets and reviewing their retirement finances before making irreversible decisions.
For many homeowners, identifying financial support they are already entitled to could be more valuable than preparing for an unconfirmed property reform.
Frequently Asked Questions About DWP Pensioner Home Ownership Rules Changes 2027
Will the DWP introduce a new home ownership rule in April 2027?
No new nationwide Pension Credit rule counting the ordinary value of a pensioner’s main home has been confirmed. The announced April 2027 changes primarily concern pension and benefit rates.
Can I claim Pension Credit if my house is worth £500,000?
Potentially, yes. The value of your main home is normally disregarded. Eligibility depends on your assessable income, savings and other circumstances.
Will the DWP force pensioners to sell their homes?
There is no announced general DWP policy requiring pensioners to sell their primary homes to qualify for Pension Credit. Separate financial assessment rules can apply to residential care.
How much savings can pensioners have in 2027?
The first £10,000 of assessable capital is normally ignored for Pension Credit. Above that, deemed weekly income is calculated at £1 for each £500 or part of £500.
Does owning a second property affect Pension Credit?
Yes, it can. A second property’s assessable net value may count as capital, although specific exemptions and temporary disregards can apply.
Will Pension Credit increase in 2027?
The Government has announced a 3.9% increase in the standard minimum guarantee, bringing it to £247.30 weekly for single pensioners and £377.40 for couples.
Can pensioners receive Pension Credit after releasing equity from their homes?
They may remain eligible, but accessible money received through equity release can affect their capital assessment. Individual circumstances and applicable disregards are important.